
Big Island Lava Zones Explained
By Penn Henderson, R(S)
Every property on this island sits in a lava zone. The number matters more than most buyers realize.
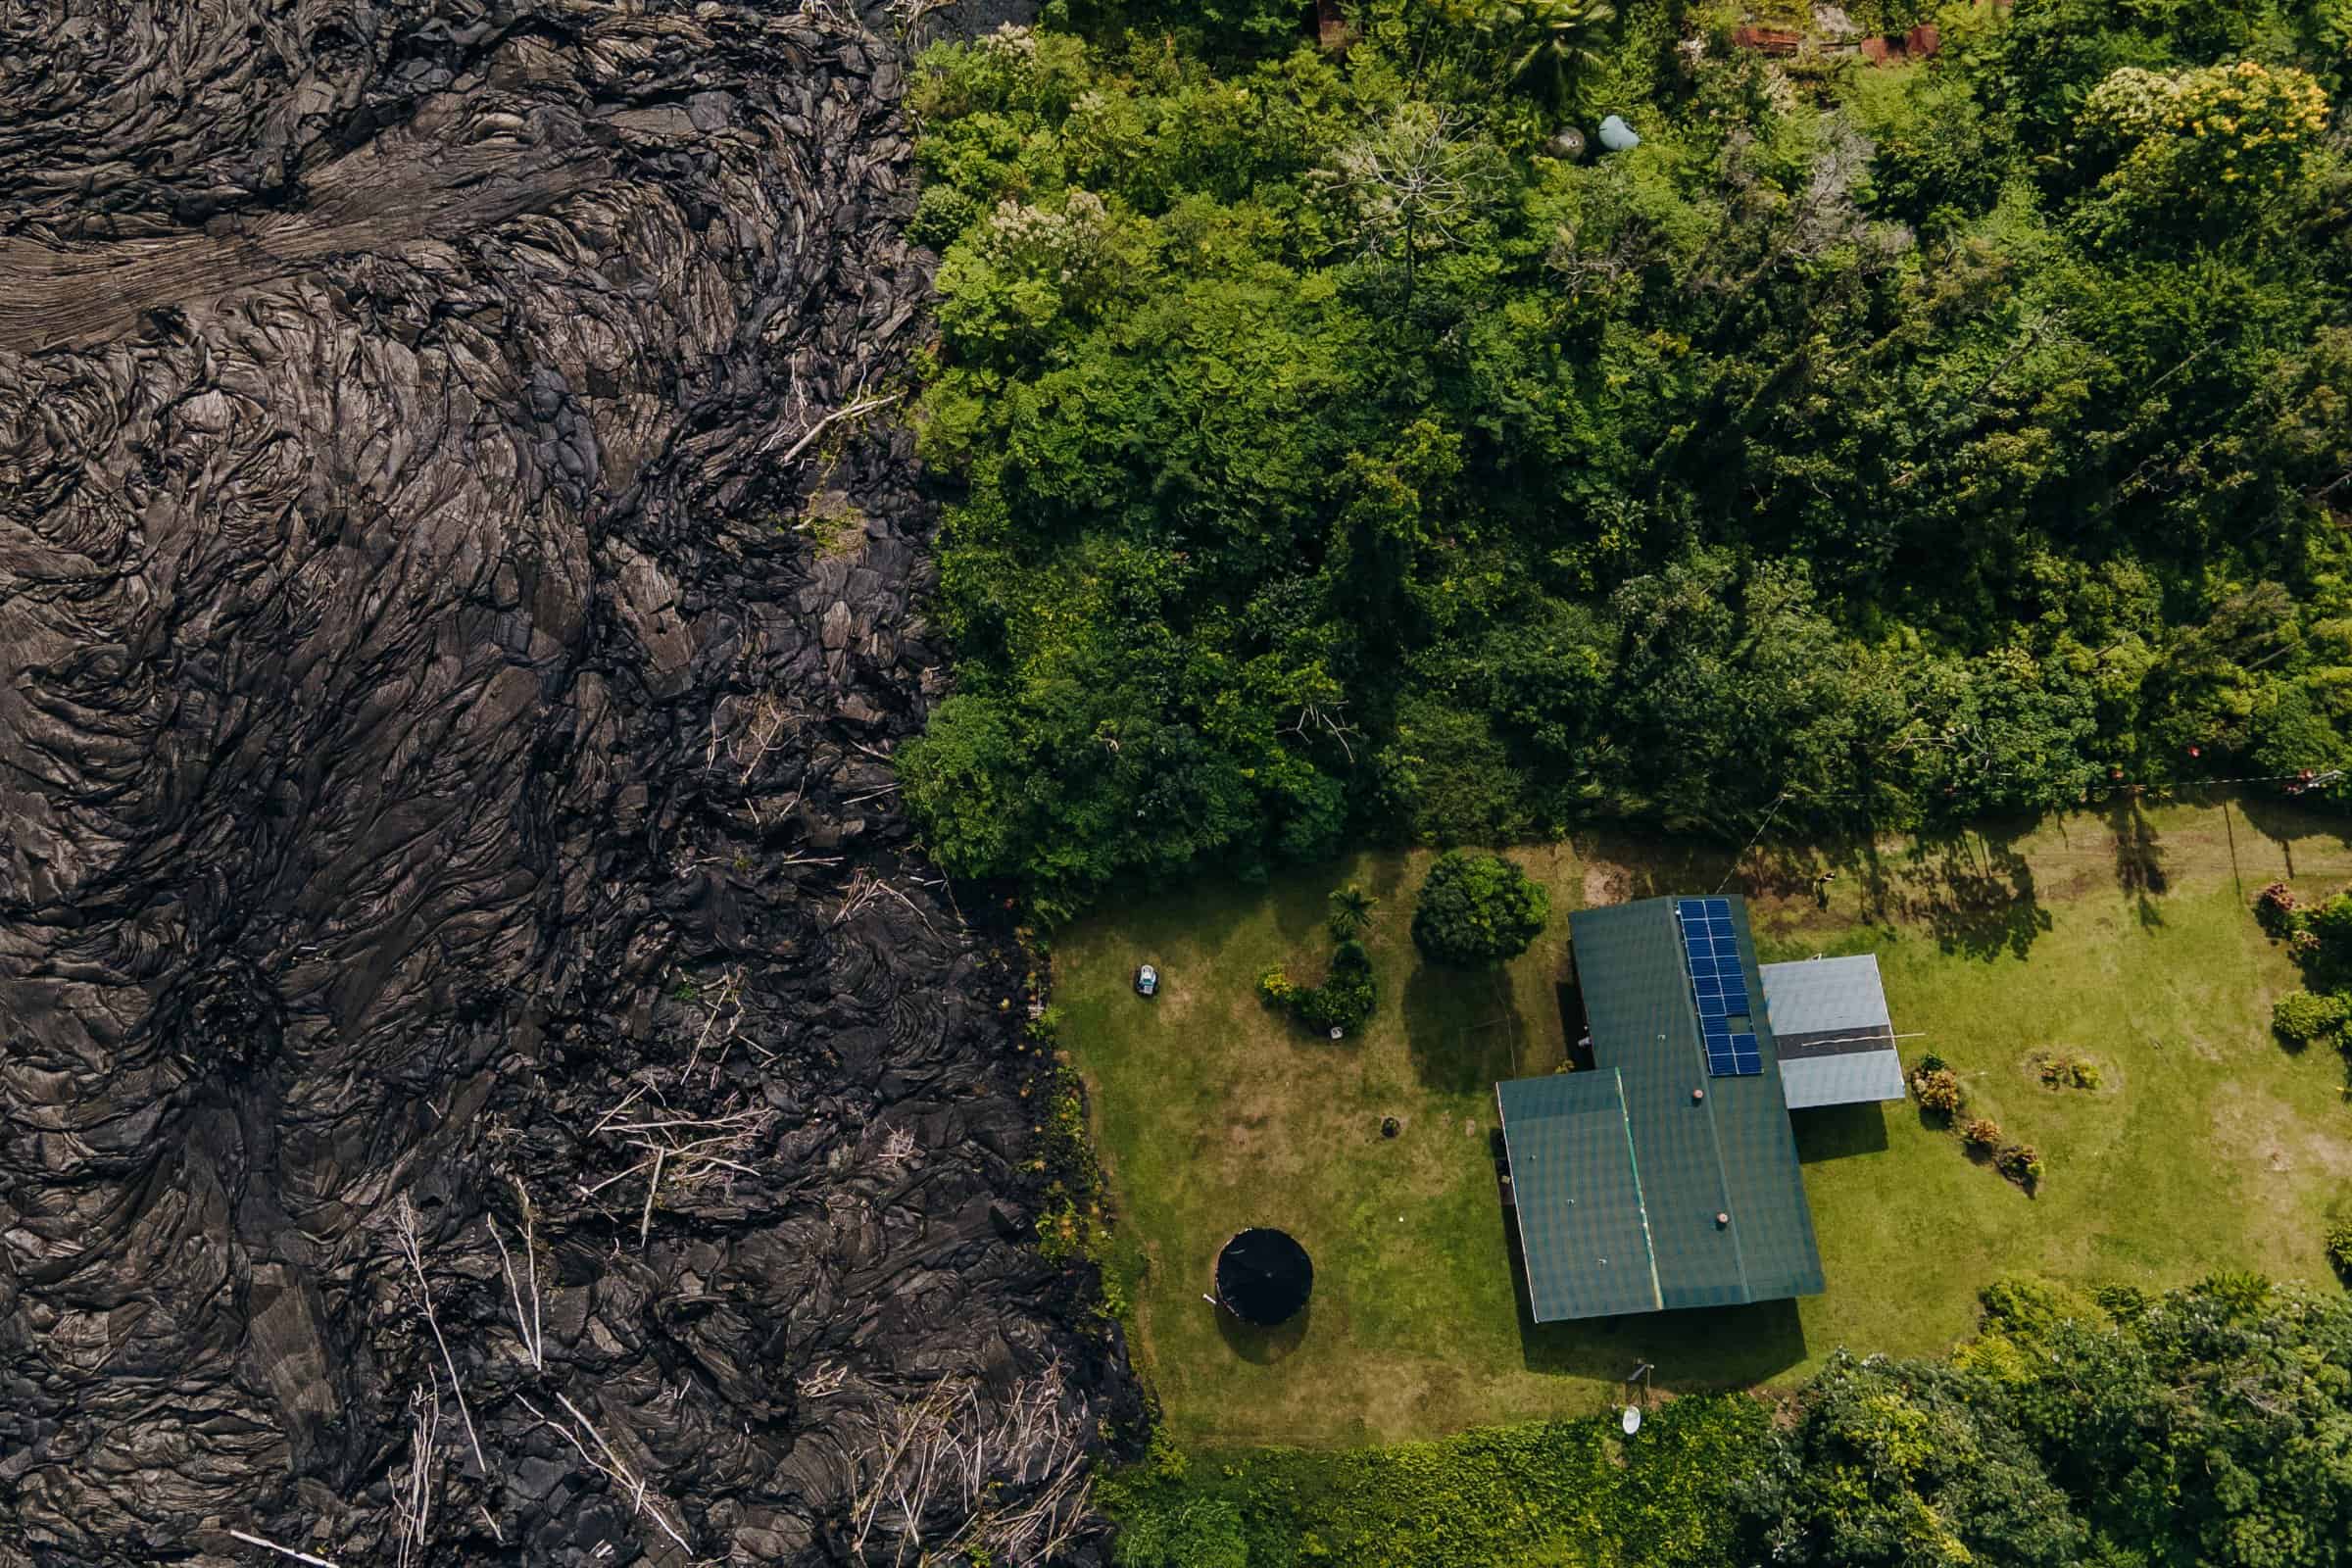
Lavaflow hazard zones are among the first things mainland buyers hear about the Big Island and among the least well explained. The zone a property sits in affects what you will pay for insurance, whether a lender will finance it, and who will want to buy it from you later. It is not a measure of whether your house will be covered in lava. It is a statistical hazard rating, and understanding what it does and does not tell you is worth an hour before you start looking at property.

Get to Know
The Nine Lava Zones
Zone 1
Covers the summits and rift zones of Kilauea and Mauna Loa, where eruptions have occurred repeatedly throughout history. This is the highest hazard rating on the island and is most affected by active flows.
Zone 2
Covers land adjacent to and downslope of the active rift zones of Kilauea and Mauna Loa. Between roughly 15 and 25% of Zone 2 has been covered by lava since 1800, and hazard increases with proximity to Zone 1.
Zone 3
Less hazardous than Zone 2 due to greater distance from active vents or terrain that makes flows less likely to arrive. Roughly 1-5% has been covered since 1800. Includes Hilo, much of South Kona, and parts of the Kohala Coast.
Zone 4
Covers all of Hualalai volcano, which has erupted far less frequently than Kilauea or Mauna Loa but is not extinct. About 5% has been covered in the last 750 years. Kailua-Kona and North Kona sit here.
Zone 5
Covers areas on Kilauea that are currently shielded from lava flows by local topography. The surrounding terrain diverts flows away, though that protection depends on ground conditions that can change over time.
Zone 6
Covers areas on Mauna Kea with only a few eruptions in the last 10,000 years. The volcano is considered dormant rather than active, and the hazard here is substantially lower than anywhere on Kilauea or Mauna Loa.
Zone 7
Covers portions of Kohala, the island’s oldest volcano, which last erupted roughly 60,000 years ago. Approximately 20% of this area was covered by lava in the intervening period, well before recorded history.
Zone 8
Covers additional areas of Kohala where only a very small share of the land has been covered by lava in the last 10,000 years. Hazard here is minimal, and standard insurance and financing are readily available.
Zone 9
Covers the remainder of Kohala, where no lava has flowed in the last 60,000 years. This is the lowest hazard rating on the island and applies to the northern end above the Kohala Coast.
Navigating Lava Zones
Buying Considerations
Where West Hawai‘i Falls
Kailua-Kona, Keauhou, Holualoa, Kalaoa, and the rest of North Kona sit in Zone 4, as does all of Hualalai, which includes the private club communities along that coast.
South Kona spans more than one zone. Kealakekua and the towns along the highway generally sit in Zone 3, while Zone 2 reaches into areas farther south and toward the Mauna Loa rift. This is the one part of West Hawaii where the zone genuinely varies property to property, and where checking it first is essential.
Kohala, at the island’s north end, has the lowest hazard ratings in Zones 7 through 9.
East Hawaii and Kau are a different picture. Puna and the Volcano area include Zone 1 and Zone 2 land, and the 2018 Kilauea eruption made that concrete for anyone who had treated the ratings as abstract. Hilo sits in Zone 3.

How Lava Zones Affect Insurance
This is where the rating becomes a practical matter rather than a geological one. Most national carriers decline to write standard homeowners policies in Zones 1 and 2. Owners in those areas typically turn to the Hawaii Property Insurance Association, a state-created entity that provides basic coverage where private insurers will not, generally at a higher cost and with narrower terms.
In Zones 3 and 4, standard coverage is normally available and priced conventionally. Most of West Hawaii falls here, which is why lava zone rarely becomes an obstacle in a Kona transaction and frequently does in a Puna one.
Get a quote early. If you are buying anywhere the zone is in question, an insurance quote belongs in the first week of escrow, not the last. It is the fastest way to find out whether a purchase actually works.
How Lava Zones Affect Financing
Lenders require proof of insurability before closing. If coverage is unavailable or prohibitively expensive, the loan will not be funded, regardless of how strong your file is. That is the mechanism by which lava zones stop transactions, and it catches buyers who assumed the issue was purely about risk tolerance.
Some lenders decline to lend on Zone 1 and Zone 2 properties outright, which is one reason cash purchases are common in those areas. A Hawaii-based lender will tell you where they stand before you write an offer. A mainland lender may not know the question exists until it derails the timeline.
Should You Avoid Zones 1 and 2?
This is where the rating becomes a practical matter rather than a geological one. Most national carriers decline to write standard homeowners policies in Zones 1 and 2. Owners in those areas typically turn to the Hawaii Property Insurance Association, a state-created entity that provides basic coverage where private insurers will not, generally at a higher cost and with narrower terms.
In Zones 3 and 4, standard coverage is normally available and priced conventionally. Most of West Hawaii falls here, which is why lava zone rarely becomes an obstacle in a Kona transaction and frequently does in a Puna one.
Get a quote early. If you are buying anywhere the zone is in question, an insurance quote belongs in the first week of escrow, not the last. It is the fastest way to find out whether a purchase actually works.

FAQ
Frequently asked questions and Answers About Big Island Lava Zones
Let’s Talk
Ready to find your big island home?
Whether you are ready to buy now, planning a move a few years out, or just starting to learn the island, I would welcome a conversation. No pressure and no obligation.
When we talk, you can expect a focused conversation about what you are trying to accomplish, an honest read on the communities and price points that actually fit, a walkthrough of how the process works here, and straight answers to every question you ask.
